Concurrent Audit in Banks: Coverage, Reporting and Critical Checkpoints
For anyone preparing for the Certified Accounting and Audit Professional (CAAP) exam, concurrent audit in banks is one of those topics that sounds procedural but carries real exam weight, because it sits at the intersection of RBI supervision policy and day-to-day branch control. Concurrent audit is a near-real-time check on transactions as they happen, run alongside normal branch operations rather than after the books are closed. This article walks through the coverage rule, who can be appointed, what gets checked daily and monthly, and how findings flow up to the Audit Committee of the Board.
🔍 Scope and Coverage: The 50% Rule
RBI's guidelines on the concurrent audit system in commercial banks do not require every branch to be audited continuously. Instead, they set a business-volume threshold: banks must ensure that branches and business units brought under concurrent audit together account for not less than 50% of the bank's aggregate advances and deposits. This is a coverage-by-value test, not a headcount test, so a bank can satisfy it by covering a smaller number of very large branches rather than a large number of small ones.
Selection is meant to be risk-based rather than arbitrary. Branches with large or concentrated advances, high-value or high-volume transactions, and business lines that are inherently harder to supervise remotely get priority. Treasury operations, both domestic and foreign exchange, are invariably included regardless of size because a single mispriced deal or unauthorised position can create outsized loss. Currency chests, credit card operations, clearing and back-office settlement functions, and branches that have gone unusually long without a full inspection are also common candidates. For background on how concurrent audit fits among the various audit types a bank runs, the chapter on bank audit and various types of audits in banks is worth revisiting before the exam.
💡 Exam Tip: If a question asks for the minimum coverage figure, the answer is 50% of advances and deposits taken together, not 50% of branches.
👥 Who Can Be Appointed as Concurrent Auditor
RBI leaves the choice of auditor to the bank's board-approved policy, but within guardrails meant to protect independence. External chartered accountant firms are the most common choice, especially for large or high-risk branches, because they bring an outside perspective and are not embedded in the branch's own reporting chain. Many banks also draw on their own retired officers for concurrent audit assignments, since retired staff understand internal processes well, but RBI expects safeguards here: rotation of assignments, a cap on how much of the total concurrent audit workload goes to retired staff, and a bar on auditing a branch where the person recently served.
What is not acceptable is self-review: the audit of a branch's transactions should never be entrusted to staff currently posted at that same branch, since that defeats the entire purpose of an independent, contemporaneous check. Serving employees of the bank can be deployed for concurrent audit, but typically at a different branch or unit from their own posting, and under the oversight of the inspection and audit function rather than the local branch head. This appointment discipline connects closely with the broader risk-based approach to supervision covered in risk based supervision: a new approach.
⚠️ Common Mistake: Candidates often assume concurrent audit is always done by an external CA firm. In practice, a bank's own retired employees, subject to safeguards, are equally permitted.
📋 Daily and Monthly Checking: What Gets Verified
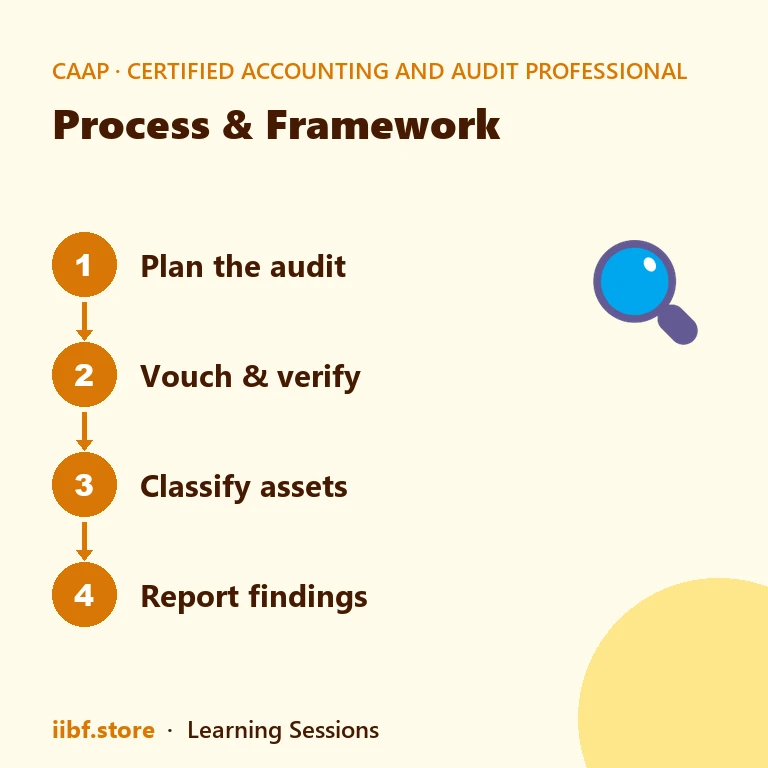
Concurrent audit is built around continuous, transaction-level checking rather than a sample review months later. On a daily basis, the auditor typically verifies cash transactions above threshold limits, high-value fund transfers, sanctioned versus disbursed advances, documentation completeness for new loans, adherence to KYC and AML norms on account opening and large transactions, and any deviation from sanctioned terms such as interest rate or margin. Foreign exchange deals, where posted, are checked for rate application, limit compliance and timely reporting.
On a monthly cycle, the auditor consolidates observations into a structured report covering areas like income leakage, asset classification and provisioning triggers, revenue audit points, and compliance with internal circulars. This monthly reporting rhythm is what separates concurrent audit from a one-off inspection visit, since irregularities get flagged while they are still fresh and correctable rather than surfacing a year later in a statutory audit. Readers who want the accounting mechanics behind income and expenditure checks should pair this with classification of income and expenditure, since several concurrent audit checkpoints are really tests of correct classification.
Serious irregularities, suspected fraud, or anything with a regulatory reporting angle are not held back for the monthly cycle; they get escalated immediately outside the routine schedule. Readers preparing the fraud angle of this subject should also see our companion piece on fraud reporting in banks, which covers the auditor's specific duty once such a red flag surfaces.
📊 Reporting Lines and How Concurrent Audit Differs From Other Audits
Concurrent audit reports do not go straight to the board. They route first through the bank's inspection and audit department, which consolidates findings across all covered branches, tracks compliance and rectification, and periodically places a summarised position before the Audit Committee of the Board (ACB). The ACB reviews coverage percentage, quality of the audit, major irregularities, and the status of corrective action, making concurrent audit one of the recurring inputs into the board's overall assurance framework.
It is worth being precise about how this differs from the bank's other audit layers, because exam questions frequently test the distinction. Internal inspection is periodic and retrospective, reviewing a branch's systems, controls and overall compliance typically once a year, well after the transactions occurred. Statutory audit, done by external chartered accountants under the Banking Regulation Act and Companies Act framework, is an annual exercise whose objective is to opine on whether the financial statements give a true and fair view, for the benefit of shareholders and regulators. Concurrent audit sits apart from both: it exists purely as a management tool for early detection at the transaction level, has no reporting obligation to external stakeholders, and does not issue an audit opinion on the financial statements. For the bigger picture of how these audit layers fit together, revisit bank audit and various types of audits in banks, and for the statutory-audit reporting angle, see our guide to the Long Form Audit Report in bank statutory audit.
📌 Remember: Concurrent audit checks transactions as they happen; internal inspection reviews the branch periodically; statutory audit opines on the annual financial statements.
| Parameter | Concurrent Audit | Internal Inspection | Statutory Audit |
|---|---|---|---|
| Timing | Near-real-time, ongoing | Periodic (usually annual) | Annual, post year-end |
| Conducted by | CA firms / eligible retired or serving staff | Bank's inspection department | External chartered accountants |
| Reports to | Audit Committee of the Board | Audit Committee of the Board | Shareholders / regulators |
| Issues an audit opinion on financial statements | ✘ | ✘ | ✔ |
| Minimum RBI coverage benchmark | ✔ (50% of advances + deposits) | No fixed % (risk-based cycle) | ✔ (statutory requirement) |
📚 Why This Matters Beyond the Exam
Concurrent audit is often the first line of defence that catches a documentation gap, a limit breach, or a suspicious pattern before it turns into a reportable fraud or a large provisioning hit. For a practising banker, understanding its coverage logic also explains why some branches feel like they are "always being audited" while others rarely see an external auditor: it is a deliberate, risk-weighted allocation rather than a rotation of convenience. This ties directly into everyday accounting hygiene as well, since many concurrent audit checkpoints such as reconciliation of suspense entries connect back to basics covered in bank reconciliation statement. CAAP candidates should also keep an eye on adjacent compliance themes; our guide to trade-based money laundering from the International Trade Finance syllabus shows how concurrent audit checks and AML screening overlap at branches handling trade transactions. For a running view of related CAAP topics, browse the Certified Accounting and Audit Professional tag hub.
🧠 Practice MCQs: Concurrent Audit in Banks
Q1. What is the minimum share of a bank's aggregate advances and deposits that RBI expects to be covered under the concurrent audit system? (a) 30% (b) 40% (c) 50% (d) 70%
Answer: (c) — RBI requires concurrent audit coverage of not less than 50% of the bank's total advances and deposits business.
Q2. Concurrent audit findings are periodically placed before which body? (a) Risk Management Committee (b) Audit Committee of the Board (c) Nomination Committee (d) Credit Sanctioning Committee
Answer: (b) — Consolidated concurrent audit reports go through the inspection department to the Audit Committee of the Board.
Q3. Which statement best distinguishes concurrent audit from statutory audit? (a) Concurrent audit opines on true and fair view of accounts (b) Concurrent audit is a near-real-time transaction check, statutory audit is an annual financial statement audit (c) Statutory audit runs daily at branch level (d) Concurrent audit happens only after the financial year closes
Answer: (b) — Concurrent audit is contemporaneous and operational; statutory audit is periodic and opines on the financial statements.
Q4. Which business is invariably brought under concurrent audit regardless of branch size, due to inherent risk? (a) Treasury operations, domestic and forex (b) Savings-bank-only branches (c) Branches with no credit exposure (d) Branches under renovation
Answer: (a) — Treasury operations carry outsized risk from a single deal or position and are covered irrespective of size.
Q5. Who, subject to RBI's independence safeguards, may be engaged for concurrent audit assignments? (a) Only the branch's own current staff (b) External CA firms or, with conditions, the bank's own retired employees (c) The branch manager personally (d) Any walk-in customer
Answer: (b) — Both external chartered accountant firms and, subject to rotation and caps, retired employees are permitted.
Want chapter-wise mock tests with 100+ MCQs? Start practising free →
❓ Frequently Asked Questions
Is concurrent audit mandatory for every bank branch?
No. RBI does not require every branch to be under concurrent audit; instead, banks must ensure that the branches and units covered together account for not less than 50% of aggregate advances and deposits, prioritising high-risk and high-value business.
How is concurrent audit different from internal inspection?
Concurrent audit checks transactions close to when they occur for early error and fraud detection, while internal inspection is a periodic, retrospective review of a branch's overall systems, controls and compliance, typically once a year.
Can a bank's retired staff be appointed as concurrent auditors?
Yes, subject to RBI's safeguards on independence and rotation, banks may engage their own retired employees for concurrent audit alongside external chartered accountant firms, provided a person does not audit a branch where they recently served.
Who ultimately reviews concurrent audit reports?
Findings are consolidated by the bank's inspection and audit department and placed periodically before the Audit Committee of the Board, with serious or fraud-related irregularities escalated immediately outside the routine reporting cycle.
Concurrent audit is one of the more scenario-heavy topics in the CAAP syllabus, and questions tend to reward precision on the coverage rule, appointment eligibility, and the reporting chain rather than rote definitions. Strengthen your grip on the surrounding accounting fundamentals with the chapter on accounting process, then put your understanding to the test with a full mock at iibf.store's course library or head straight to iibf.store/tests for chapter-wise practice.
Prefer revising from a printed book?
Chapter-wise books with MCQs after every chapter — minimal pages, complete coverage, delivered anywhere in India. Every book has a free sample to read first.



Practice this topic
Take a free mock test, download chapter PDFs, or watch a video class — all included on iibf.store.