Pre-Packaged Insolvency Resolution Process (PPIRP) for MSMEs
The pre-packaged insolvency resolution process (PPIRP) is a faster, lower-cost insolvency route built specifically for micro, small and medium enterprises (MSMEs) hit by financial stress. Introduced through the Insolvency and Bankruptcy Code (Amendment) Act, 2021, PPIRP lets an MSME's existing promoters keep running the business while quietly negotiating a resolution plan with financial creditors, before ever formally approaching the Adjudicating Authority. For JAIIB and CAIIB candidates, understanding how the pre-packaged insolvency resolution process differs from the standard Corporate Insolvency Resolution Process (CIRP) on eligibility, creditor thresholds and timelines is a recurring exam theme.
🏛️ What Is PPIRP and Why It Was Introduced
PPIRP was inserted into the Insolvency and Bankruptcy Code, 2016 by the IBC (Amendment) Act, 2021 as an entirely new Chapter III-A, spanning Sections 54A to 54P. The government notified it in April 2021, and the Insolvency and Bankruptcy Board of India (IBBI) subsequently framed detailed PPIRP regulations, as a direct response to pandemic-era stress in the MSME sector — millions of small businesses faced cash-flow shocks but could not afford the cost, disruption and reputational drag of a full-blown Corporate Insolvency Resolution Process. Rather than creating a parallel law, Parliament chose to graft a lighter, MSME-only mechanism onto the existing IBC architecture, so most CIRP concepts (moratorium, resolution professional, committee of creditors, Adjudicating Authority) still apply, just in a compressed and debtor-friendly form.
The logic is "pre-packaged" because much of the negotiation between the corporate debtor and its financial creditors happens informally before the formal process is admitted by the National Company Law Tribunal (NCLT). By the time an application is filed, a base resolution plan is often already broadly agreed, which is why PPIRP can run to a strict 120-day outer limit compared to the far longer CIRP timeline. Students revising the evolution of the Insolvency and Bankruptcy Code should treat PPIRP as the most recent major structural addition to the Code after the original 2016 enactment.
📋 Eligibility Criteria for MSMEs Under PPIRP
PPIRP is not available to every corporate debtor — it is restricted to a corporate debtor classified as a micro, small or medium enterprise under Section 7(1) of the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006. A corporate debtor must be in default of an amount of at least Rs 10 lakh, which is the minimum default threshold prescribed for triggering PPIRP under Section 54A. This is deliberately kept lower than the general IBC default threshold that applies to ordinary CIRP filings, reflecting the smaller scale of MSME balance sheets.
Beyond the MSME classification and the default threshold, the corporate debtor must not have undergone a CIRP or a PPIRP in the preceding three years, must not currently be undergoing liquidation, and its directors or partners must not be disqualified. Critically, before the application for PPIRP can even be filed, the corporate debtor needs the approval of unrelated financial creditors — those not related to the corporate debtor — holding at least 66% in value of the financial debt, given through a resolution passed within the preceding two weeks. A special resolution of members or a resolution of at least three-fourths of partners is also required, and the proposed resolution professional and the base resolution plan must both be approved before filing. Eligibility under Section 29A of the Code applies exactly as it does in CIRP, so promoters or connected persons who are disqualified — for example due to a wilful-default classification or a related non-performing asset — cannot bid for or run the process. Readers building on the initiation of Corporate Insolvency Resolution Process (CIRP) chapter will notice PPIRP borrows this creditor-approval logic but pushes it earlier, before admission rather than after.
💡 Exam Tip: Memorise the trio together — Sections 54A to 54P, the Rs 10 lakh default threshold, and the 66% unrelated-financial-creditor approval. This exact combination is a favourite in MCQs testing PPIRP eligibility.
🤝 Debtor-in-Possession, Creditor-in-Control: PPIRP's Hybrid Model
The single biggest conceptual difference between PPIRP and ordinary CIRP is who runs the company during the process. Under CIRP, the moment the process is admitted, the management of the corporate debtor effectively vests in an interim resolution professional and then a resolution professional, with the board of directors suspended — a creditor-in-possession model administered through a professional. PPIRP flips this: it is designed as a "debtor-in-possession, creditor-in-control" framework. The existing board and management continue to run day-to-day operations throughout the process, which limits disruption to a small business's operations, employees, suppliers and customers.
Control does not disappear from creditors, however — it simply changes form. A resolution professional is still appointed to oversee the process, verify claims, conduct the base resolution plan's evaluation and report to the committee of creditors (CoC), which retains real decision-making power, including the ability to remove management from the debtor's affairs if it acts fraudulently or to the detriment of creditors. This is why PPIRP is described as having creditor-in-control features layered on top of debtor possession, rather than being purely a debtor-friendly free pass. Another distinctive feature is the base resolution plan: unlike CIRP, where a resolution professional invites competing resolution plans from the market through a request for resolution plans, PPIRP starts with a plan submitted by the corporate debtor itself. If this base plan impairs the claims of operational creditors, or offers less than liquidation value, the CoC can invite competing plans through a Swiss challenge mechanism, giving other resolution applicants a chance to outbid the promoter's own proposal. Candidates comparing this against the roles and duties of IRP and RP chapter should note the RP's supervisory role is lighter here than in a full CIRP.
⚠️ Common Mistake: Students often assume PPIRP is open to any small company facing default. It is not — only a corporate debtor that meets the MSME classification test under Section 7(1) of the MSMED Act, 2006 is eligible, regardless of how small the company otherwise appears.
⏱️ The 120-Day PPIRP Timeline
Speed is the entire point of PPIRP, and the Code enforces this with a hard 120-day outer limit measured from the date of commencement of the process. Within this window, the corporate debtor and resolution professional must submit the approved resolution plan to the Adjudicating Authority within 90 days of the commencement date. The Adjudicating Authority — the NCLT — then has a further 30 days to examine and approve (or reject) the plan, completing the 90-plus-30 structure that adds up to the 120-day ceiling. This is dramatically shorter than the CIRP timeline, which runs to 180 days with a one-time 90-day extension and a judicially recognised outer limit of 330 days including litigation time.
Much of PPIRP's speed advantage comes from front-loading negotiation into the pre-commencement phase: because unrelated financial creditors holding 66% in value must already have approved the base resolution plan and the resolution professional before the application is even filed, the formal 120-day clock starts with most of the heavy lifting already done. Compare this against the commencement of CIRP chapter, where the timeline only begins once the NCLT admits the application and appoints an interim resolution professional from scratch — there is no equivalent pre-agreed base plan in ordinary CIRP.
📌 Remember: Break the 120-day PPIRP limit into its two components — 90 days to submit the resolution plan to the Adjudicating Authority, plus 30 days for the Adjudicating Authority's approval. Numerical and sequencing questions frequently test this split.
⚖️ PPIRP vs CIRP: Key Differences
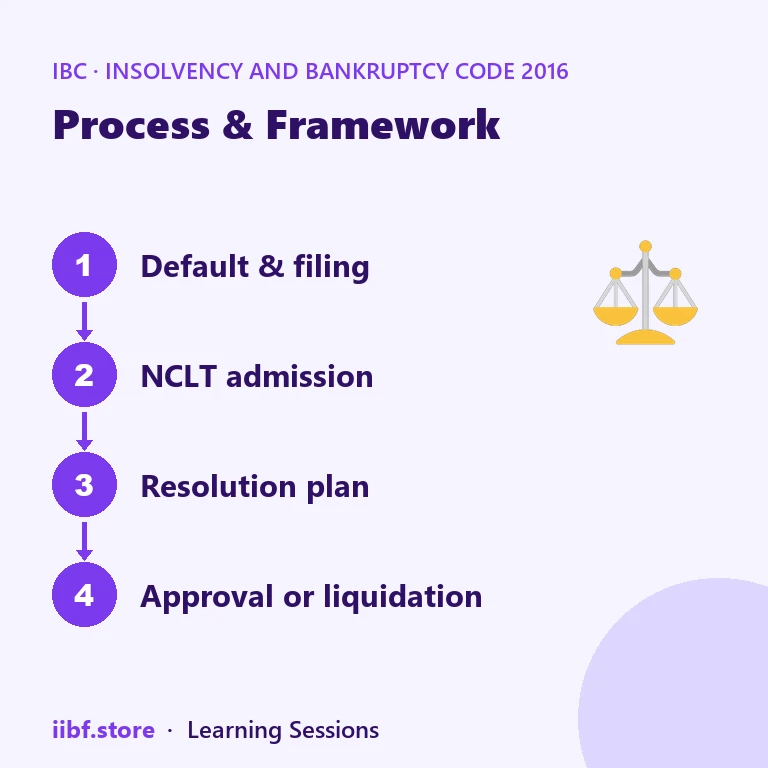
Because IBBI exam questions love direct comparisons, it helps to line up PPIRP against ordinary CIRP feature by feature. Both processes ultimately aim at resolving the corporate debtor rather than pushing it straight to liquidation, both operate under the overall framework of the Insolvency and Bankruptcy Code, 2016, and both apply the Section 29A eligibility bar to anyone hoping to control the resolution outcome. Where they diverge sharply is on who can use the process, who runs the company meanwhile, how the resolution plan originates, and how long the whole exercise is allowed to take.
| Feature | PPIRP | CIRP |
|---|---|---|
| Legal basis | Chapter III-A, Sections 54A-54P | Part II, Chapter II |
| Who can apply | MSMEs only (Section 7(1), MSMED Act 2006) | Any corporate debtor |
| Management control | Debtor-in-possession ✅ | Vests in RP; board suspended ❌ |
| Minimum default | Rs 10 lakh | Higher default threshold under Section 4 |
| Creditor approval to initiate | 66% value of unrelated FCs, pre-filing ✅ | Not required pre-filing ❌ |
| Resolution plan origin | Base plan by corporate debtor + Swiss challenge | Open invitation via RFRP |
| Outer timeline | 120 days (90+30) | Up to 330 days |
| Section 29A applies | Yes ✅ | Yes ✅ |
Reading this table alongside the structure of the IBC chapter makes it clear that PPIRP is not a substitute law but a specialised fast lane built into the same statute, sharing its committee-of-creditors machinery and its Section 29A guardrails. For a deeper look at how creditor voting thresholds like the 66% figure operate more broadly across the Code, see our piece on committee of creditors voting: 51%, 66% and 90% rules.
🧠 Practice MCQs: Pre-Packaged Insolvency Resolution Process (PPIRP) for MSMEs
Q1. Under the IBC (Amendment) Act, 2021, the Pre-Packaged Insolvency Resolution Process was inserted as which chapter of the Code? (a) Chapter III, Sections 33-54 (b) Chapter III-A, Sections 54A to 54P (c) Chapter IV, Sections 60-77 (d) Chapter II-A, Sections 20A-20P
Answer: (b) — PPIRP is Chapter III-A, covering Sections 54A to 54P of the IBC.
Q2. What is the minimum amount of default required to trigger PPIRP for an eligible MSME? (a) Rs 1 lakh (b) Rs 10 lakh (c) Rs 1 crore (d) Rs 50 lakh
Answer: (b) — Section 54A prescribes a minimum default of Rs 10 lakh to initiate PPIRP.
Q3. Before filing a PPIRP application, the corporate debtor must obtain approval from unrelated financial creditors holding what percentage in value? (a) 51% (b) 60% (c) 66% (d) 90%
Answer: (c) — At least 66% in value of unrelated financial creditors must approve before the application is filed.
Q4. PPIRP is available only to corporate debtors classified as MSMEs under which provision? (a) Companies Act, 2013, Section 2(85) (b) MSMED Act, 2006, Section 7(1) (c) IBC, 2016, Section 3 (d) SARFAESI Act, 2002, Section 2
Answer: (b) — Eligibility is tied to MSME classification under Section 7(1) of the MSMED Act, 2006.
Q5. What is the outer time limit for completion of PPIRP, and how is it split? (a) 90 days, no split (b) 180 days (90+90) (c) 120 days (90 days to AA + 30 days for AA approval) (d) 330 days (180+90+60)
Answer: (c) — PPIRP must conclude within 120 days: 90 days to submit the plan to the Adjudicating Authority and 30 days for its approval.
Want chapter-wise mock tests with 100+ MCQs? Start practising free →
❓ Frequently Asked Questions on PPIRP
What does PPIRP stand for and when was it introduced?
PPIRP stands for Pre-Packaged Insolvency Resolution Process. It was inserted into the Insolvency and Bankruptcy Code, 2016 by the IBC (Amendment) Act, 2021, as Chapter III-A, Sections 54A to 54P, notified in April 2021.
Who can apply for PPIRP?
Only a corporate debtor classified as an MSME under Section 7(1) of the MSMED Act, 2006, that is in default of at least Rs 10 lakh, has approval from unrelated financial creditors holding 66% in value, and meets the other eligibility conditions including Section 29A compliance.
How is PPIRP different from a normal CIRP?
PPIRP is a debtor-in-possession process with creditor-in-control features — existing management keeps running the company, a base resolution plan is filed upfront by the debtor, and the whole process must finish within 120 days. CIRP hands management to a resolution professional, invites plans openly from the market, and can run up to 330 days.
What happens if the base resolution plan under PPIRP is inadequate?
If the base resolution plan impairs operational creditors' dues or offers less than liquidation value, the committee of creditors can invite competing resolution plans through a Swiss challenge mechanism before finalising the plan.
PPIRP gives financially stressed MSMEs a genuine second chance — speed, continuity of management and lower cost, without diluting the creditor safeguards that make the IBC credible. For related reading, see how the fresh start process under IBC serves individual debtors, how the look-back period under IBC protects the estate from avoidance transactions, and how fraud reporting in banks intersects with insolvency red flags. Browse every article tagged under the Insolvency and Bankruptcy Code 2016 hub, or put this chapter to the test with a free mock on iibf.store/tests and structured coverage inside the JAIIB course.
Prefer revising from a printed book?
Chapter-wise books with MCQs after every chapter — minimal pages, complete coverage, delivered anywhere in India. Every book has a free sample to read first.



Quick quiz on this topic
5 exam-style questions from our free test bank — check yourself before you move on.
Practice this topic
Take a free mock test, download chapter PDFs, or watch a video class — all included on iibf.store.