Positive Pay System in India: RBI Rules Every Banker Must Know
Cheque fraud did not disappear when banking went digital — it simply moved. That is why the Positive Pay System in India matters for every JAIIB and CAIIB candidate: it is one of the few RBI-mandated controls that bridges paper instruments with digital verification. Under this system, an account holder issuing a cheque above a threshold value must electronically confirm the cheque's key details — number, date, amount, and payee — before it is presented for payment. The paying bank then cross-checks this confirmation against the physical cheque at the clearing stage, and any mismatch triggers a hold or return. This article breaks down how the mechanism works, the RBI rules that govern it, and the exam facts you need to lock in before your next mock test.
🏦 What Is the Positive Pay System in India?
The Positive Pay System in India was introduced by the Reserve Bank of India in 2020 as a fraud-prevention layer sitting on top of the existing Cheque Truncation System (CTS). Instead of relying purely on manual signature verification and image-based scrutiny at the drawee bank, Positive Pay adds a second, independent data channel: the account holder themselves. When you issue a cheque of a qualifying value, you log into net banking, mobile banking, an ATM, or an SMS-based channel and submit the cheque particulars — the same details printed on the instrument. This becomes a reference record sitting in the bank's core banking system, separate from the physical cheque that later travels through the clearing house. For candidates studying the overview of digital banking channels, Positive Pay is a good example of a control that uses digital rails to protect a legacy paper instrument rather than replacing it outright. It complements — but is distinct from — payment-rail comparisons such as NEFT RTGS IMPS differences, because cheques still clear through a separate CTS grid even in 2026.
📋 How the Positive Pay System Works — Step by Step
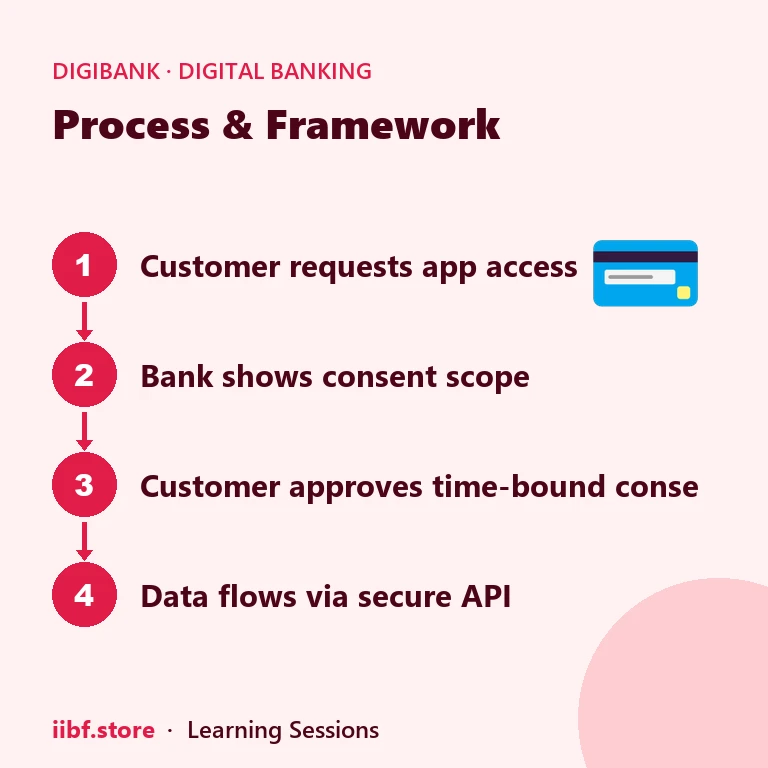
The mechanics of Positive Pay follow a consistent sequence across banks, even though the exact channel names vary. First, the drawer (the person issuing the cheque) fills in the cheque as usual — payee name, amount in words and figures, date, and signature. Second, before handing the cheque over, the drawer submits the same core fields through a designated digital channel: internet banking, the bank's mobile app, an IVR/SMS gateway, or occasionally a branch-assisted form. Third, this submitted data is stored as a reference entry tagged to the cheque number. Fourth, when the cheque is presented for payment — either by the payee's bank through CTS or over the counter — the paying bank's system automatically matches the physical cheque image and MICR data against the stored Positive Pay confirmation. If every field matches, the cheque proceeds through normal clearing. If there is a mismatch on amount, payee name, or date, the cheque is flagged, and depending on the bank's policy it may be returned or held for manual confirmation with the drawer. Banks typically give customers a window — commonly 24 to 78 hours before the cheque is presented — within which the Positive Pay confirmation must be submitted, or the cheque risks being treated as unconfirmed at clearing.
💡 Exam Tip: Remember that Positive Pay is drawer-initiated and voluntary/mandatory by value threshold — it is not the bank generating the check, the account holder is the one confirming cheque details before clearing.
⚖️ RBI Rules, Thresholds and Implementation Across Banks
RBI's original direction asked banks to enable Positive Pay for all account holders issuing cheques of ₹50,000 and above, while leaving banks free to make it mandatory beyond a higher value — most large banks set the mandatory threshold at ₹5,00,000 and above for CTS cheques, with voluntary participation encouraged below that. Cooperation from the National Payments Corporation of India was built into the design: NPCI operates the central Positive Pay System infrastructure that facilitates data exchange between the presenting bank and the paying bank during CTS clearing, so confirmations move as part of the same clearing cycle rather than through a parallel manual process. Banks were required to build customer-facing confirmation channels and to send SMS/email alerts reminding customers to confirm high-value cheques, as laid out in RBI's original Positive Pay System circular. For a full account of how this sits within the retail digital banking syllabus, see the Retail Banking - Digital Banking Class 12 chapter, which covers CTS and related RBI directions in sequence with mobile and internet banking topics.
| Feature | Traditional Cheque Clearing | Positive Pay System |
|---|---|---|
| Verification source | Signature + image scrutiny only | Drawer-submitted data + signature/image |
| Fraud on altered amount/payee | ❌ Often undetected until reconciliation | ✅ Flagged automatically at clearing |
| Who initiates confirmation | Not applicable | Account holder, before presentation |
| Mandatory threshold | None | ₹50,000+ (bank-defined, often ₹5,00,000+) |
| Central infrastructure | CTS grid only | CTS grid + NPCI Positive Pay layer |
| Customer action needed | ❌ None beyond issuing the cheque | ✅ Digital confirmation of cheque details |
⚠️ Common Mistake: Students often assume Positive Pay System in India replaces CTS. It does not — it is an additional confirmation layer that rides on top of the existing Cheque Truncation System, not a separate clearing mechanism.
🛡️ Fraud Prevention: Positive Pay vs Cheque Truncation Risks
Before Positive Pay, the most common cheque frauds in India involved altering the payee name or inflating the amount after a genuine cheque had already been signed — changes that were often invisible to a bank teller relying only on image-based CTS scrutiny. This system directly targets this gap by creating an independent, drawer-verified record that cannot be tampered with after submission. If a fraudster intercepts a physical cheque and alters the amount, the paying bank's system will detect the discrepancy against the stored Positive Pay entry and can halt payment before funds move — shifting fraud detection from "after the loss" to "before settlement." This sits alongside broader institutional defences covered under types of security controls in banks, since Positive Pay is essentially a preventive control layered on transaction authentication. It is worth contrasting this cheque-specific protection with instrument-level protections used elsewhere in retail banking, such as those built into prepaid payment instruments in India, where the risk surface and RBI's regulatory approach differ considerably because there is no physical instrument to forge.
📌 Remember: Positive Pay is a bank-side and customer-side responsibility together — banks must build the confirmation infrastructure, and customers must actually use it for the protection to work.
🎯 Exam Focus: Positive Pay System in India for JAIIB/CAIIB
For JAIIB and CAIIB, this topic tends to appear in Digital Banking and Retail Banking papers as either a direct definitional question or a scenario-based question asking you to identify which fraud type it prevents. Examiners frequently test the confirmation channel list (internet banking, mobile banking, ATM, SMS/IVR), the role of NPCI as the central facilitator during CTS clearing, and the distinction between a mandatory and voluntary threshold. Another frequently tested angle compares digital banking growth generally — including how mobile banking channels are used for Positive Pay confirmation — against newer entrants in the space, such as how neo banks in India approach fraud prevention without legacy cheque infrastructure at all. Candidates should also be comfortable explaining why Positive Pay is considered a low-cost, high-impact control: it requires no new hardware for customers and reuses banks' existing digital channels, which is exactly the kind of efficiency argument IIBF examiners like to test in application-based questions.
🧠 Practice MCQs: Positive Pay System
Q1. The Positive Pay System in India was introduced by which regulator? (a) NPCI (b) SEBI (c) Reserve Bank of India (d) IBA
Answer: (c) — RBI introduced the Positive Pay System directive in 2020 as a cheque fraud-prevention measure.
Q2. Under the Positive Pay System, who is primarily responsible for submitting cheque confirmation details? (a) The payee bank (b) NPCI (c) The account holder/drawer (d) The clearing house
Answer: (c) — The drawer submits cheque details electronically before the instrument is presented for payment.
Q3. RBI's Positive Pay System advised banks to make confirmation mandatory for cheques valued at or above: (a) ₹5,000 (b) ₹50,000 (c) ₹5,00,000 only (d) ₹1,00,00,000
Answer: (b) — RBI's baseline direction covers cheques of ₹50,000 and above, with banks free to raise the mandatory threshold further.
Q4. Which infrastructure facilitates data exchange for Positive Pay confirmations during CTS clearing? (a) SWIFT (b) NPCI (c) BBPS (d) ONDC
Answer: (b) — NPCI operates the central layer that passes Positive Pay confirmations between presenting and paying banks within the CTS cycle.
Q5. What type of cheque fraud does Positive Pay primarily prevent? (a) Stolen chequebook usage before any cheque is written (b) Post-issuance alteration of amount or payee name (c) Online phishing of net-banking credentials (d) ATM card skimming
Answer: (b) — By matching drawer-submitted details against the presented cheque, Positive Pay catches tampering done after the cheque was signed.
Want chapter-wise mock tests with 100+ MCQs? Start practising free →
Is the Positive Pay System in India mandatory for every cheque?
No. RBI's baseline direction applies to cheques of ₹50,000 and above, and individual banks may raise the mandatory threshold, commonly to ₹5,00,000, while keeping confirmation voluntary for smaller amounts.
What happens if a customer does not confirm a cheque under Positive Pay?
Policies vary by bank, but an unconfirmed high-value cheque is typically flagged or returned for manual verification rather than being cleared automatically, protecting both the bank and the customer from undetected alteration.
Does the Positive Pay System replace the Cheque Truncation System?
No. It works alongside CTS as an additional data-matching layer; cheques still move through the CTS grid for image-based clearing, with Positive Pay confirmations checked as a parallel step.
Which channels can customers use to submit Positive Pay confirmations?
Most banks accept confirmations through internet banking, mobile banking apps, ATMs, and SMS or IVR-based channels, giving customers multiple ways to confirm cheque details before presentation.
The Positive Pay System in India is a compact but exam-heavy topic precisely because it sits at the intersection of regulation, fraud control, and digital channel design — the three pillars IIBF loves to test together. Revisit the confirmation workflow, the RBI threshold rules, and the NPCI infrastructure role until you can explain all three without notes, then head over to the digital banking article hub for related reads, or take a free chapter-wise mock test to check how well the concept has actually stuck.
Quick quiz on this topic
5 exam-style questions from our free test bank — check yourself before you move on.
Practice this topic
Take a free mock test, download chapter PDFs, or watch a video class — all included on iibf.store.
Keep reading